Loading subject page…


2,159 views


Video Summary: What Is Risk in Bond Valuation
Portfolio managers across Wall Street face a fundamental challenge: understanding risk bond valuation to protect client assets while maintaining competitive returns. When evaluating corporate debt instruments from companies like General Electric or Ford Motor Company, professionals must assess five critical risk categories that directly impact portfolio performance and investor confidence. Default risk threatens principal recovery, while interest rate fluctuations can erode market value overnight. Liquidity constraints during market stress can force disadvantageous exits, and inflation can silently erode real returns. Watch the full video on JoVE Coach to master this concept with expert-led visuals and step-by-step explanations.
Corporate treasurers and portfolio managers operating in today's volatile interest rate environment face unprecedented challenges in bond valuation. When BlackRock or Vanguard evaluates a $500 million corporate bond issuance, their risk assessment directly impacts fund performance and client retention. The concept of risk in bond valuation encompasses five interconnected factors that determine investment attractiveness and portfolio allocation decisions.
Default risk represents the primary concern for institutional investors evaluating corporate debt. When analyzing companies like Tesla or Netflix, investment professionals examine debt-to-equity ratios, cash flow coverage, and industry-specific vulnerabilities. Credit rating agencies provide initial guidance, but sophisticated investors conduct independent analysis to identify potential downgrades before they impact market pricing. A single notch downgrade can trigger institutional selling requirements and immediate portfolio losses.
Federal Reserve policy decisions create systematic interest rate risk across all fixed-income securities. Professional bond managers employ duration matching strategies to minimize price volatility when yields fluctuate. For instance, a 10-year Apple corporate bond experiences approximately 8% price decline for each 1% interest rate increase. Treasury departments at Fortune 500 companies actively monitor this risk when issuing debt, timing issuances around anticipated Fed actions to optimize borrowing costs.
Market stress events, such as the 2020 COVID-19 disruption, highlighted liquidity risk in corporate bond markets. Even high-quality issuers like Microsoft or Johnson & Johnson experienced temporary liquidity constraints as institutional investors sought cash positions. Professional portfolio managers maintain diversified maturity ladders and emergency liquidity protocols to avoid forced selling during market dislocations.
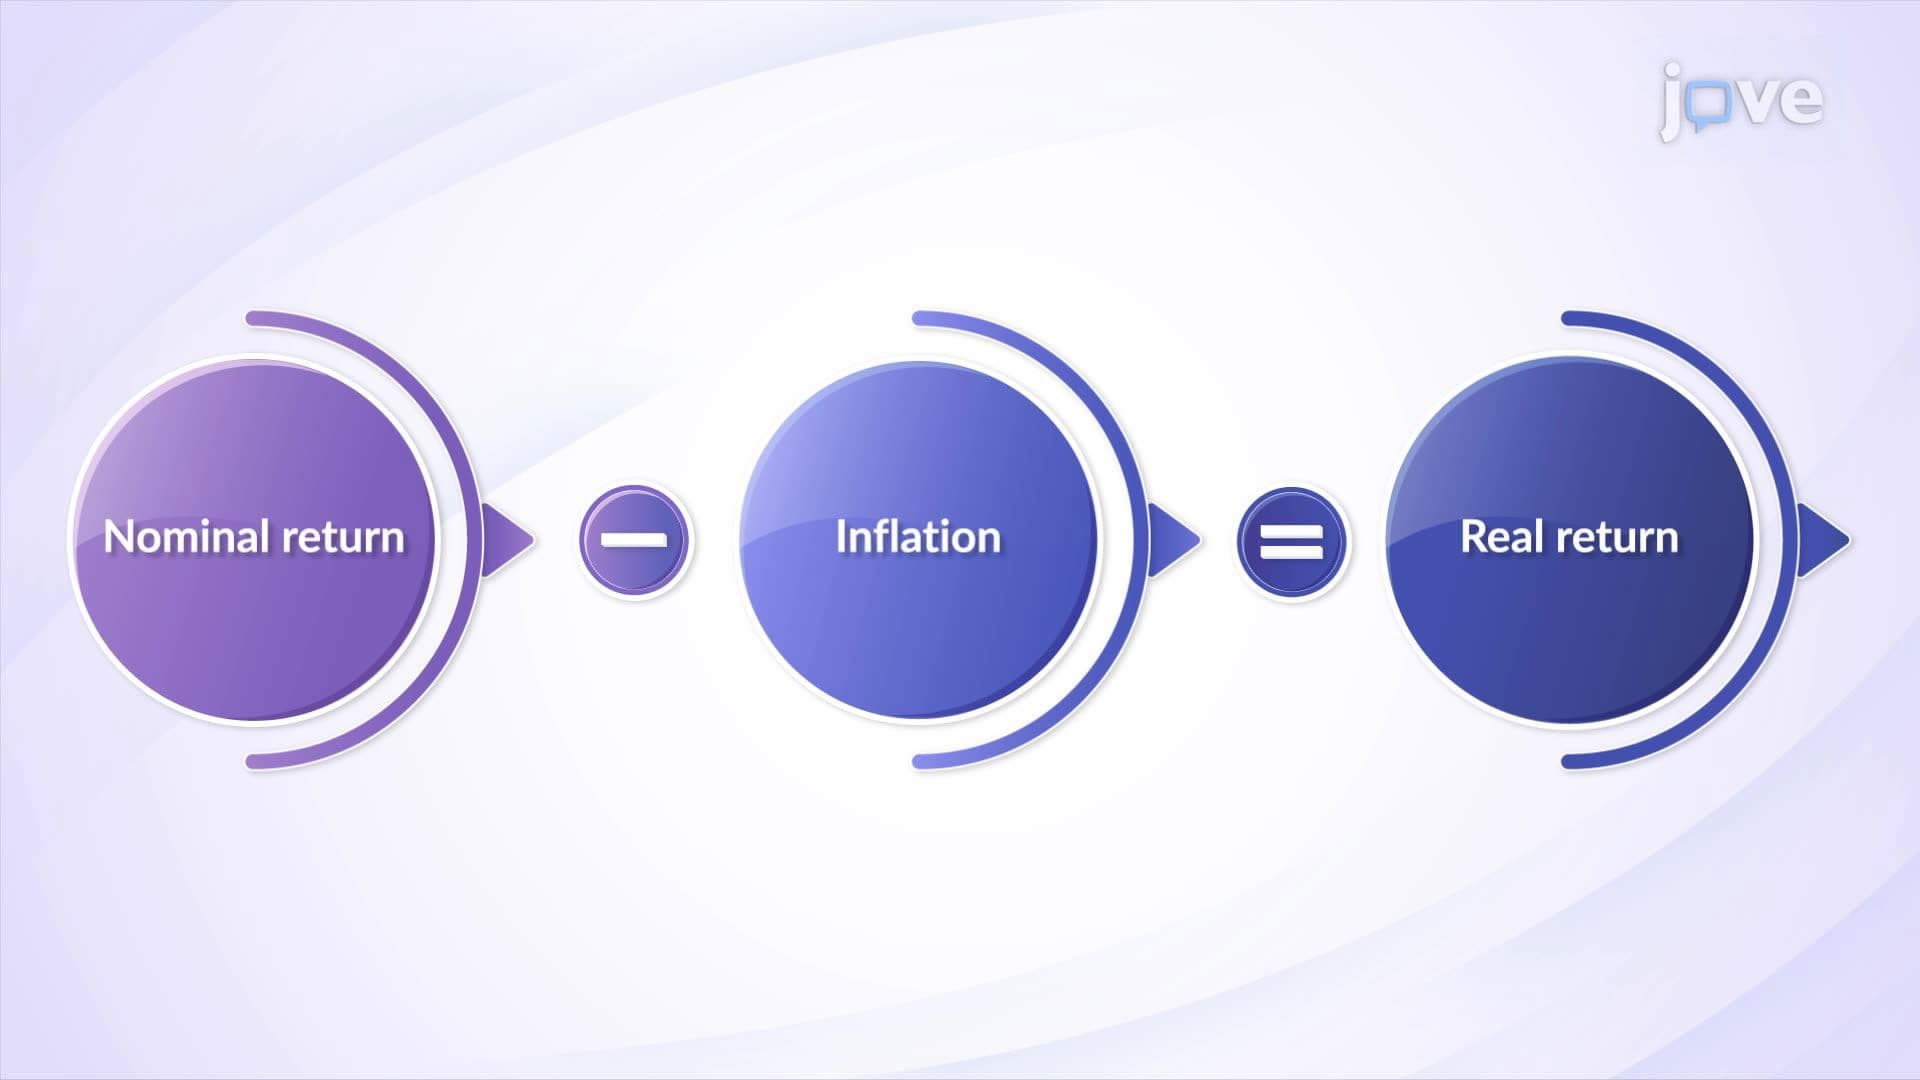
Inflation erodes fixed coupon payments' purchasing power over time, particularly concerning for pension funds and insurance companies with long-term obligations. Investment committees increasingly evaluate Treasury Inflation-Protected Securities (TIPS) and floating-rate corporate bonds as portfolio hedges against unexpected inflation acceleration.
Related Micro-courses